What Northwest Florida Seniors Should Know in 2026
| A comprehensive guide to preventive visits, physical exams, billing rules, and unexpected charges Prepared by Mark Garrett | AJ Health and Wealth |
Serving Pace, Milton, Pensacola, and surrounding Northwest Florida communities
Part One: Understanding Medicare’s Preventive Visits
You schedule what you believe is a free Medicare wellness visit. You arrive at your doctor’s office, answer questions, discuss your health, and perhaps mention a new pain or another medical concern. Several weeks later, a bill arrives.
How can a visit that Medicare describes as costing nothing produce an out-of-pocket charge?
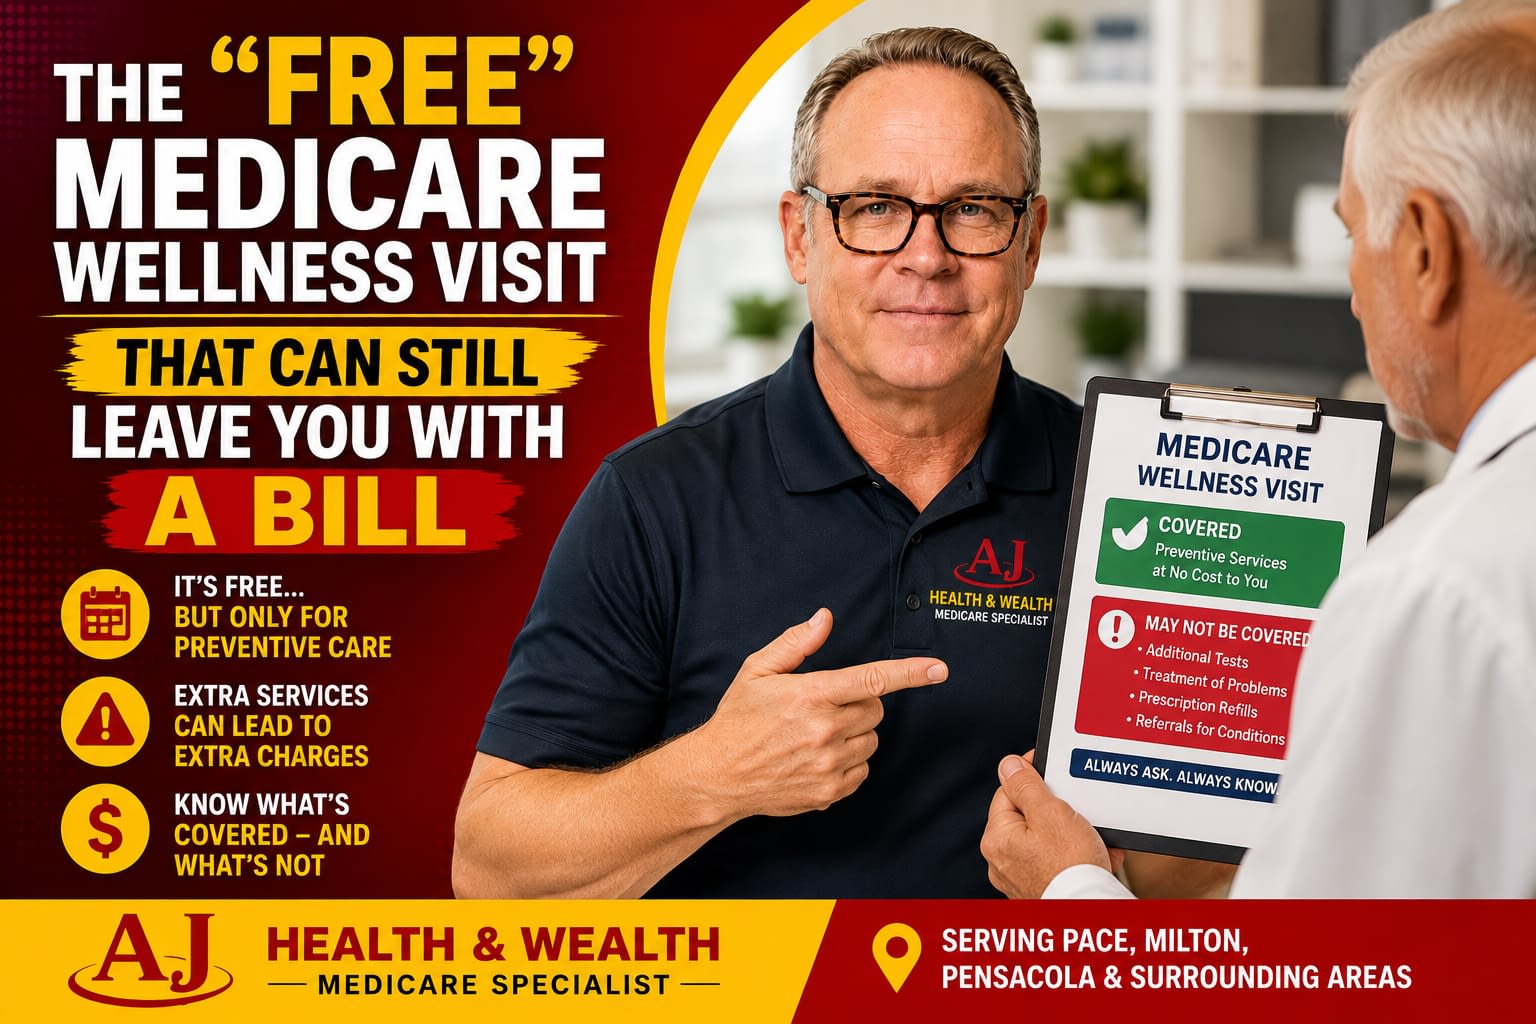
The answer is that a Medicare Annual Wellness Visit is a specific preventive benefit—not a traditional physical examination and not an unlimited medical appointment. The preventive portion may cost nothing when Medicare’s requirements are met, but additional services performed during the same appointment can be billed separately.
This distinction surprises Medicare beneficiaries throughout Pace, Milton, Pensacola, and the rest of Northwest Florida. Understanding what Medicare means by “wellness visit” can help you prepare for the appointment, receive the preventive care available to you, and reduce the chance of an unexpected bill.
Three Visits That Are Commonly Confused
People often use the terms “physical,” “checkup,” and “wellness visit” interchangeably. Medicare does not. Under Medicare, these descriptions can refer to three different types of appointments:
- The one-time “Welcome to Medicare” preventive visit.
- The yearly Medicare Annual Wellness Visit.
- A routine physical examination.
They may sound similar, but their eligibility rules, covered services, and potential costs are different.
The “Welcome to Medicare” Preventive Visit
The Initial Preventive Physical Examination, commonly called the “Welcome to Medicare” preventive visit, is available once during the first 12 months that a person has Medicare Part B.
Despite the word “physical” in its formal name, this appointment is not a comprehensive, head-to-toe physical examination. Its purpose is disease prevention, early detection, and the creation of a preventive-care plan.
According to the Centers for Medicare & Medicaid Services, Medicare pays for only one Initial Preventive Physical Examination during a beneficiary’s lifetime, and it must take place within the first 12 months after Part B coverage begins. If that 12-month period passes, the unused visit does not carry over for later use. The beneficiary may become eligible for an Annual Wellness Visit instead.
During the “Welcome to Medicare” visit, the healthcare provider may:
- Review the patient’s medical and social history.
- Review potential risk factors for depression and substance-use disorders.
- Record height, weight, blood pressure, and body mass index.
- Perform a simple vision test.
- Discuss the patient’s ability to function safely.
- Review current medications and healthcare providers.
- Discuss preventive screenings and vaccines.
- Provide referrals for additional care when appropriate.
- Offer information about advance directives.
- Develop a written plan identifying recommended preventive services.
Medicare states that the beneficiary generally pays nothing for the covered preventive visit when the provider accepts Medicare assignment. The Part B deductible does not apply to the preventive visit itself.
However, additional tests, treatments, or services performed during the appointment may create a separate charge. If Medicare covers those additional services, the Part B deductible and coinsurance may apply. If Medicare does not cover them, the patient could be responsible for the full cost.
The Medicare Annual Wellness Visit
After a beneficiary has had Part B for more than 12 months, Medicare Part B covers a yearly Annual Wellness Visit. Medicare generally covers this visit once every 12 months, provided the beneficiary has not received a “Welcome to Medicare” visit or another Annual Wellness Visit during the preceding 12 months.
The Annual Wellness Visit is designed to create or update a personalized prevention plan based on the individual’s health, family history, and risk factors. Medicare describes it as a conversation-based preventive visit rather than a routine physical examination.
The appointment normally begins with a Health Risk Assessment. This questionnaire helps the healthcare provider understand the patient’s overall health and identify risks that may require preventive attention.
The assessment may address:
- Current health conditions.
- Prescription medications, over-the-counter drugs, and supplements.
- Family medical history.
- Tobacco and alcohol use.
- Nutrition and physical activity.
- Emotional and behavioral health.
- Ability to perform everyday activities.
- Fall risks and home-safety concerns.
- Hearing or vision concerns.
- Social circumstances that may affect health.
- The patient’s other physicians and healthcare providers.
During the Annual Wellness Visit, the provider may also measure height, weight, blood pressure, and body mass index; review prescriptions; update the patient’s medical and family history; and create a schedule for appropriate screenings, vaccines, and other preventive services.
Medicare also includes a cognitive assessment intended to look for possible signs of dementia or other cognitive impairment. This is not necessarily a complete diagnostic evaluation. If the provider identifies a concern, a separate, more detailed cognitive assessment may be recommended and billed under different Medicare rules.
The visit may also include a review of depression risk, fall risk, functional ability, and opioid use. The provider can discuss advance-care planning and prepare a written preventive-care checklist for the coming years.
The first Annual Wellness Visit is sometimes called the “initial” Annual Wellness Visit. Later yearly visits are called “subsequent” Annual Wellness Visits. These terms describe the first and later wellness visits; they should not be confused with the one-time Initial Preventive Physical Examination offered during a beneficiary’s first 12 months of Part B.
CMS uses separate billing codes for the first Annual Wellness Visit and subsequent visits:
- G0438: First Annual Wellness Visit.
- G0439: Subsequent Annual Wellness Visit.
These codes help Medicare identify which preventive service was provided. They do not turn the appointment into a comprehensive physical examination.
What the Annual Wellness Visit Does Not Include
The most important fact for beneficiaries to understand is that the Annual Wellness Visit is not a traditional annual physical.
A routine physical may include a more extensive hands-on examination of the heart, lungs, abdomen, skin, reflexes, ears, nose, throat, and other body systems. It might also include laboratory work or other testing.
Original Medicare specifically lists routine physical examinations among the services it generally does not cover. Some individual components of an examination may be covered when they are medically necessary or qualify as separate preventive services, but that does not mean Original Medicare covers a comprehensive annual physical as a single benefit.
The Annual Wellness Visit is primarily about prevention planning. It is intended to help the patient and provider identify risks, organize recommended screenings, review medications, and develop a plan for maintaining health.
It is not intended to provide unrestricted evaluation and treatment of every new or ongoing medical problem.
Why the Distinction Matters
Suppose a Medicare beneficiary schedules an Annual Wellness Visit and then tells the doctor about increasing shortness of breath, knee pain, dizziness, or a change in an existing medical condition. The provider may reasonably evaluate that problem during the appointment.
That evaluation can become a separate medically necessary office service in addition to the covered wellness visit. Tests, treatments, diagnostic work, or management of chronic conditions may also fall outside the preventive benefit.
The healthcare provider is not necessarily charging for the free portion twice. Instead, the claim may contain one service for the Annual Wellness Visit and another for evaluating or treating the medical concern.
Whether the patient owes anything for the additional service can depend on:
- Whether the service is covered by Medicare.
- Whether the Part B deductible has been met.
- Whether coinsurance applies.
- Whether the provider accepts Medicare assignment.
- Whether the patient has Medigap, employer coverage, Medicaid, or another secondary payer.
- Whether the patient receives coverage through a Medicare Advantage plan.
- The type of service or test performed.
- The location where the service is provided.
Medicare clearly warns that coinsurance and the Part B deductible may apply when additional tests or services are performed during the same appointment. If an added service is not covered by Medicare—such as a routine physical examination—the patient may owe the full amount.
Part Two: Avoiding Unexpected Charges and Understanding Your Coverage
The Medicare Annual Wellness Visit can be valuable. It gives beneficiaries and their healthcare providers an opportunity to review health risks, medications, preventive screenings, safety concerns, and other factors that may affect long-term health.
The problem is not the benefit itself. The problem is the gap between what many patients expect and what Medicare actually covers.
A person may hear “free yearly wellness visit” and reasonably expect a complete annual examination with no out-of-pocket costs. Under Medicare’s rules, however, the no-cost benefit applies only to the defined preventive services included in the wellness visit. Anything beyond that benefit may be billed separately.
How a $0 Wellness Visit Becomes a Billable Appointment
Consider a common situation. A beneficiary schedules an Annual Wellness Visit and mentions that a shoulder has been hurting for several weeks. The doctor examines the shoulder, discusses possible causes, recommends treatment, and orders an X-ray.
The preventive wellness portion and the evaluation of the shoulder are two different services. The practice may submit a claim for the Annual Wellness Visit and a separate claim for evaluating the new medical problem. The X-ray may create another claim.
The same issue can arise when a patient asks the provider to evaluate:
- New or worsening pain.
- Shortness of breath.
- Dizziness or balance problems.
- A skin lesion.
- Changes in blood pressure.
- Increasing fatigue.
- Medication side effects.
- An uncontrolled chronic condition.
- A new symptom requiring diagnosis or treatment.
Discussing health risks as part of prevention planning is included in the Annual Wellness Visit. Diagnosing or treating a medical condition may be a separate service.
Under Original Medicare, the beneficiary generally pays nothing for the covered Annual Wellness Visit when the provider accepts assignment. If the provider also performs a separately billable medical service, the Part B deductible and coinsurance may apply to that additional service.
For 2026, the standard Medicare Part B deductible is $283. After the deductible is met, beneficiaries with Original Medicare generally pay 20% of the Medicare-approved amount for most covered physician services when the provider accepts assignment. Supplemental coverage may help with some of that cost.
Common Services That May Create Additional Charges
Evaluation of a New or Existing Medical Problem
A provider may bill separately when the appointment includes significant evaluation or management of a medical condition beyond the preventive wellness service. The fact that both services occur during one appointment does not automatically make the medical evaluation part of the no-cost wellness benefit.
Laboratory Testing
Routine bloodwork is not automatically included in the Annual Wellness Visit. Medicare may cover certain preventive screenings when the beneficiary meets the eligibility and frequency requirements. Medicare may also cover medically necessary diagnostic laboratory tests ordered to investigate a symptom or condition.
However, the reason for the test, the type of test, how frequently it is performed, and how it is coded can affect coverage.
Medicare states that beneficiaries usually pay nothing for covered diagnostic laboratory tests. That does not mean every requested laboratory panel is covered. A test that is not medically necessary, is performed more frequently than Medicare allows, or is not included in a covered preventive benefit may create a charge.
A Routine Physical Examination
Original Medicare generally does not cover a routine head-to-toe physical examination. If a patient requests a traditional physical during the same appointment as the Annual Wellness Visit, the physical may be billed as a noncovered service.
CMS describes a routine physical as an examination performed without a relationship to the treatment or diagnosis of a particular illness, symptom, complaint, or injury. CMS states that the patient is responsible for 100% of the cost of a routine physical that Original Medicare does not cover.
Procedures and Treatments
An injection, minor procedure, wound treatment, medical device, diagnostic test, or other service may have its own coverage and cost-sharing rules. It does not necessarily become free because it was provided during a wellness appointment.
Services Performed in a Hospital-Owned Outpatient Clinic
The location of care can affect what a beneficiary pays. Under Original Medicare, an outpatient service received in a hospital outpatient department may include a separate hospital copayment or coinsurance in addition to the charge for the healthcare provider’s service.
Medicare notes that patients may pay more for certain outpatient services performed in a hospital setting than they would for the same services in a physician’s office.
The Importance of Medicare Assignment
For people with Original Medicare, it is important to ask whether the doctor or healthcare provider accepts Medicare assignment.
A provider who accepts assignment agrees to accept the Medicare-approved amount as full payment for a covered service. The provider may collect the applicable Medicare deductible and coinsurance but cannot charge more than the Medicare-approved amount for an assigned service.
A provider who does not accept assignment may require payment at the time of service and may charge more than the Medicare-approved amount for certain covered services, subject to Medicare’s limiting-charge rules.
Medicare advises beneficiaries to confirm assignment because it can reduce their out-of-pocket costs. Assignment applies to Medicare-covered services. It does not require a provider to offer a noncovered service for free.
What About an Advance Beneficiary Notice?
An Advance Beneficiary Notice of Noncoverage, or ABN, is a written notice used in Original Medicare when a provider believes Medicare is likely to deny payment for certain services.
A properly completed ABN should identify the service, explain why Medicare may not pay, and provide an estimated cost. The beneficiary can then decide whether to receive the service and accept potential financial responsibility.
However, beneficiaries should not assume that they cannot be billed unless they signed an ABN.
CMS explains that an ABN is not required before every service Medicare never covers. Because a routine physical is generally excluded from Original Medicare coverage, a provider may issue a voluntary notice as a courtesy, but the same mandatory ABN rules do not necessarily apply.
The safest approach is to ask about coverage and cost before receiving services rather than relying solely on whether the office provides an ABN.
Original Medicare, Medigap, and Unexpected Charges
A Medigap policy can help pay certain deductibles, coinsurance, and other cost-sharing amounts left by Original Medicare. The exact protection depends on the standardized Medigap plan the beneficiary has.
However, Medigap generally works with services that Original Medicare covers. If Original Medicare does not cover a routine physical or another service, a Medigap policy ordinarily will not convert that excluded service into a Medicare-covered benefit.
That distinction is important. A person may have excellent supplemental coverage and still owe the full cost of a service that Medicare does not cover.
Beneficiaries should review their policy or contact their Medigap insurer when they are unsure how a separate medical service will be handled.
Medicare Advantage Plans May Work Differently
Medicare Advantage plans must cover the medically necessary services covered by Original Medicare, including Medicare-covered preventive benefits. Plans may also offer additional benefits that Original Medicare does not cover.
For example, some Medicare Advantage plans may include a routine annual physical as an extra benefit. That does not mean every Medicare Advantage plan includes it or that the benefit works the same way under every plan.
Cost-sharing may also depend on:
- Whether the provider is in the plan’s network.
- Whether the plan is an HMO, PPO, or another plan type.
- The service provided during the appointment.
- Whether the service requires prior authorization.
- Whether the provider bills a separate office visit.
- The plan’s copayments, coinsurance, and benefit rules.
- Whether the patient follows the plan’s referral requirements.
Medicare Advantage members should consult the plan’s Evidence of Coverage and Summary of Benefits or call the member-services number on the plan identification card.
Medicare explains that Medicare Advantage plans must cover the services Original Medicare covers and may provide additional benefits. Those extra benefits and their rules vary by plan.
Seven Questions to Ask Before the Appointment
- Am I being scheduled for the “Welcome to Medicare” visit, an Annual Wellness Visit, or a routine physical?
- Does the provider accept Medicare assignment?
- Have you verified that I am eligible for the wellness visit at this time?
- Will there be a separate charge if I discuss a new symptom or ongoing medical problem?
- Are laboratory tests included, or will they be ordered and billed separately?
- Is the office part of a hospital outpatient department that may charge a facility fee?
- If I have Medicare Advantage, is the provider in my plan’s network, and will my plan cover any additional services?
These questions may not produce an exact final cost in every situation, but they can reveal when the appointment is likely to include separately billable care.
How to Prepare for the Wellness Visit
To make the appointment more useful, bring:
- A complete list of prescriptions, over-the-counter medicines, vitamins, and supplements.
- The names of physicians, specialists, pharmacies, and other healthcare providers involved in your care.
- Your family medical history.
- Immunization records, if available.
- A list of recent screenings.
- Information about falls, balance problems, memory concerns, or changes in daily functioning.
- A list of questions about preventive screenings and vaccines.
- Your Medicare card and any Medicare Advantage, Medigap, Medicaid, employer, or retiree insurance cards.
If you have a new symptom or medical concern, tell the scheduling staff before the appointment. Ask whether it should be addressed during the wellness visit, handled as a separately billed service, or scheduled as a different appointment.
Separating the visits may be clearer for billing, although it may require another trip to the doctor. The right choice depends on the urgency of the medical concern and the provider’s scheduling and billing practices. Never delay necessary medical care simply to avoid a potential copayment.
What to Do If You Receive an Unexpected Bill
First, do not assume that the bill is correct—or incorrect—based only on the total.
Review the Claim Information
People with Original Medicare should compare the bill with their Medicare Summary Notice. The Medicare Summary Notice is not a bill. It shows what the provider billed, what Medicare approved, what Medicare paid, and the maximum amount the beneficiary may owe.
Medicare Advantage members should review the Explanation of Benefits provided by the plan.
Ask the Provider for an Itemized Statement
Request an explanation of each service and charge. Ask the billing office whether the claim included both an Annual Wellness Visit and a separate office visit, test, procedure, or physical examination.
Check for Coding or Eligibility Issues
A claim can be affected by an incorrect billing code, missing information, or a wellness visit performed before the beneficiary was eligible for another one. If the provider submitted incorrect information, the office may be able to correct and resubmit the claim.
Contact Medicare or the Medicare Advantage Plan
For Original Medicare, call 1-800-MEDICARE or review the claim through a secure Medicare account. Medicare Advantage members should call the plan’s member-services department.
Appeal When Appropriate
If Medicare or a Medicare Advantage plan denies coverage and you believe the service should have been covered, you have the right to appeal.
For Original Medicare, the Medicare Summary Notice provides the deadline and instructions. Medicare recommends contacting the provider first when a service is denied to determine whether the claim was submitted correctly.
The Bottom Line for Northwest Florida Medicare Beneficiaries
The Medicare Annual Wellness Visit is an important preventive benefit, but its name can create the wrong expectation. It is not a comprehensive physical, and the promise of a $0 preventive visit does not mean that every service performed during that appointment will cost nothing.
Before visiting a medical practice in Pace, Milton, Pensacola, or elsewhere in Northwest Florida, identify the type of appointment being scheduled. Confirm that the provider accepts Medicare assignment or participates in your Medicare Advantage network. Ask how additional symptoms, examinations, laboratory tests, and procedures will be billed.
A few questions before the appointment can make the difference between receiving a useful preventive benefit with clear expectations and opening an unexpected medical bill several weeks later.
How AJ Health & Wealth Can Help
Mark Garrett is a licensed independent Medicare broker serving Escambia and Santa Rosa counties, including Pace, Milton, Pensacola, Jay, and Gulf Breeze. AJ Health and Wealth helps local Medicare beneficiaries understand their coverage choices, compare plan options, and know what to expect before an appointment—so preventive care stays free and other services don’t come as a surprise.
Medicare plan benefits, provider networks, costs, and coverage rules can vary, so beneficiaries should review their individual coverage before receiving care.
Questions About Your Medicare Coverage?
Talk with a licensed local agent at AJ Health and Wealth—no cost, no obligation.
Schedule Your Free Medicare Consultation →Internal Links
- Medicare Part A Hospital Coverage Explained
- What to Know About the Medicare Initial Enrollment Period
- Medicare Insurance Agent in Pensacola, FL