Mark Garrett, AJ Health and Wealth
You picked a Medicare Advantage plan during Annual Enrollment.
January arrives.
Then something happens.
Your doctor isn’t in the network like you thought. A prescription costs considerably more than expected. The copays don’t look nearly as attractive when you actually start using the plan. Or maybe you simply realize:
“I think I picked the wrong Medicare Advantage plan.”
Are you stuck with it for the entire year?
Not necessarily.
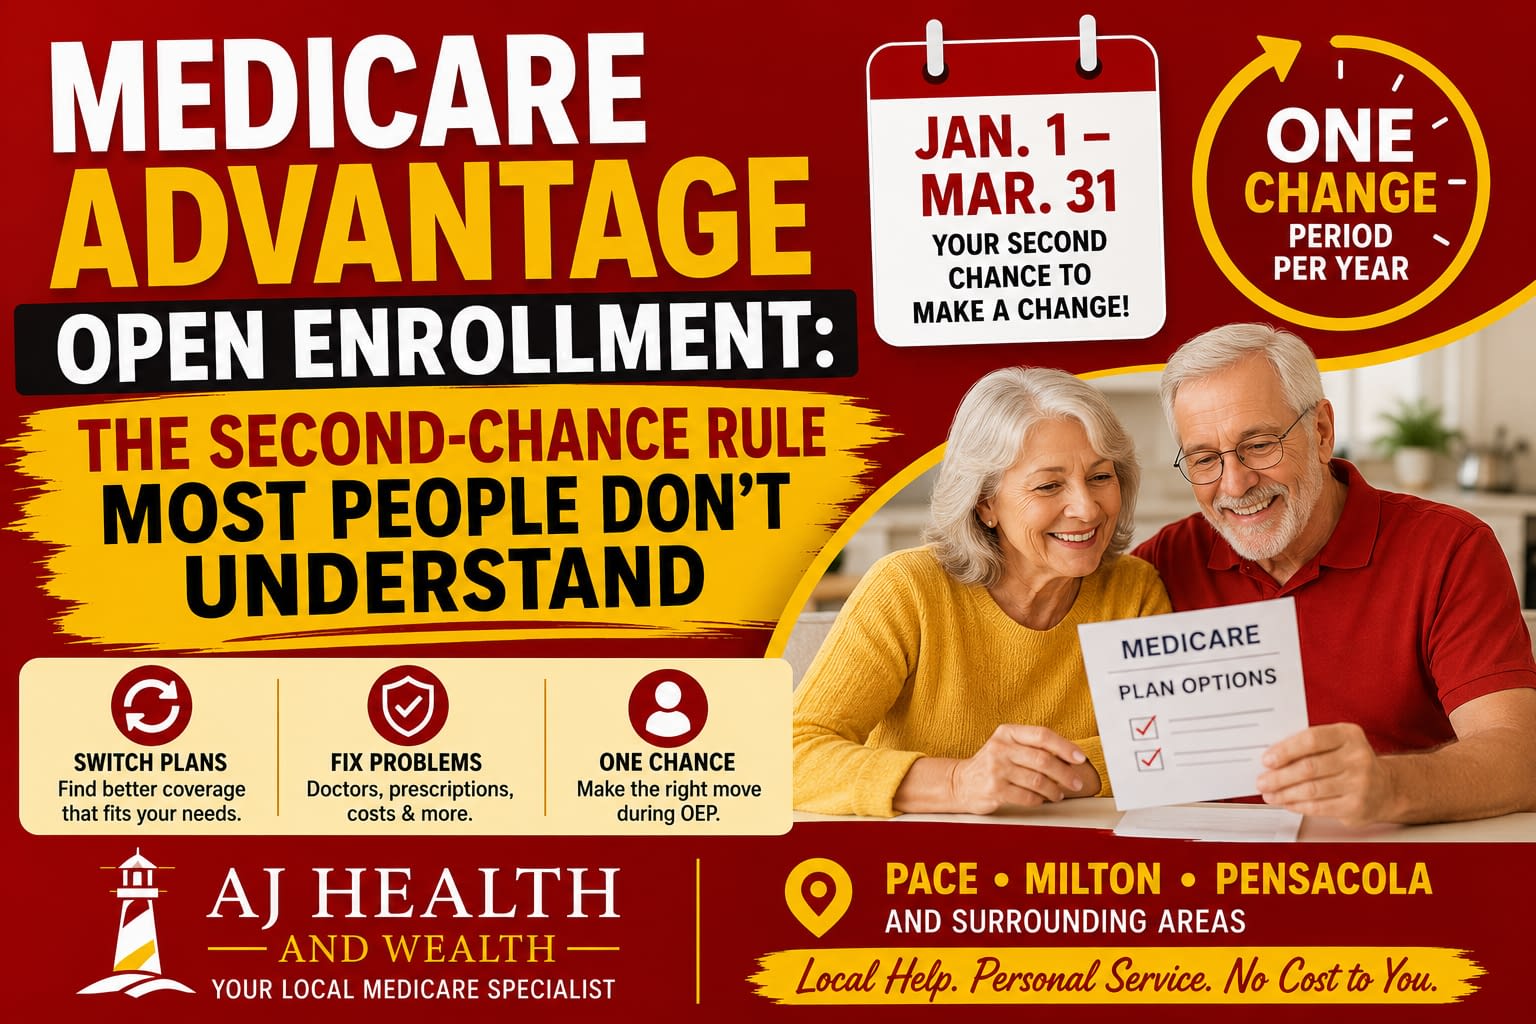
Medicare provides an important second opportunity called the Medicare Advantage Open Enrollment Period, or MA OEP.
It runs from January 1 through March 31 each year, but there is a lot of confusion about what this enrollment period actually allows you to do.
Let’s clear that up.
First: OEP Is NOT Another AEP
This is probably the most important thing to understand.
During the fall Annual Enrollment Period, which runs from October 15 through December 7, Medicare beneficiaries have broad opportunities to change Medicare Advantage and Part D coverage.
The Medicare Advantage Open Enrollment Period is different.
OEP is specifically for people who are already enrolled in a Medicare Advantage plan.
If you’re enrolled in Original Medicare and simply decide in February that you’d like to try Medicare Advantage, OEP generally doesn’t give you that opportunity.
Think of OEP more like a correction window for Medicare Advantage members.
What Can You Do During Medicare Advantage OEP?
If you’re enrolled in a Medicare Advantage plan, OEP generally gives you two important options.
Option #1: Switch to another Medicare Advantage plan
Maybe the plan you selected isn’t working the way you expected.
Perhaps:
- Your doctor isn’t participating
- Your preferred hospital isn’t in-network
- A specialist you need isn’t available
- Your prescriptions are more expensive than expected
- Copays are higher than you anticipated
- Another Medicare Advantage plan better fits your needs
During OEP, you can generally make one change to another Medicare Advantage plan.
That new plan can be an MA plan with prescription drug coverage or, where appropriate, an MA-only plan.
Option #2: Leave Medicare Advantage and return to Original Medicare
You can also use OEP to leave your Medicare Advantage plan and return to Original Medicare — Parts A and B.
If you’re leaving a Medicare Advantage plan that included prescription drug coverage, Medicare provides a coordinating opportunity to enroll in a stand-alone Part D prescription drug plan.
But there’s an important issue people often overlook.
Returning to Original Medicare Doesn’t Automatically Guarantee You a Medigap Plan
This is where consumers need to be especially careful.
Someone may think:
“I’ll just leave Medicare Advantage, go back to Original Medicare and buy a Medicare Supplement.”
That may be possible.
But depending on your circumstances and state rules, you may not have a guaranteed right to purchase every Medicare Supplement plan available to you without medical underwriting.
Medigap enrollment rules are different from Medicare Advantage enrollment rules.
Your initial Medigap Open Enrollment Period generally provides very strong protections when you’re first eligible, and certain circumstances can create guaranteed-issue rights later.
But simply leaving Medicare Advantage during OEP does not automatically mean every person has unlimited guaranteed access to a Medicare Supplement.
Before dropping Medicare Advantage because you intend to purchase Medigap, understand whether you can actually obtain the Medicare Supplement coverage you want.
Don’t cancel first and ask questions later.
You Generally Get ONE OEP Change
Another common misconception is that January through March becomes a three-month Medicare shopping season.
It doesn’t.
During the Medicare Advantage Open Enrollment Period, an eligible Medicare Advantage member generally gets one election.
Suppose you switch from Plan A to Plan B in January.
You don’t ordinarily get to switch to Plan C in February and Plan D in March using OEP.
That makes the decision important.
Before making your one change, verify the details.
When Does Your New Coverage Begin?
Changes made during the Medicare Advantage Open Enrollment Period generally become effective on the first day of the month following the plan’s receipt of your enrollment request.
For example, if an eligible enrollment change is completed in February, the new coverage would generally begin March 1.
That means you should continue using your existing coverage until the new coverage becomes effective.
Why Someone Might Discover a Problem in January
This is exactly why OEP can be valuable.
A Medicare Advantage plan can look perfectly acceptable on paper during AEP.
Then January comes and you actually begin using it.
That’s when reality can expose problems.
“My doctor says they don’t take my plan.”
This is one of the first things I’d investigate.
There is an important difference between a physician saying:
“We take Medicare.”
and:
“We participate in your specific Medicare Advantage plan and network.”
Those aren’t necessarily the same thing.
“My prescription costs more than I expected.”
Prescription coverage can vary based on:
- Formulary placement
- Drug tier
- Preferred versus standard pharmacy
- Prior authorization
- Step therapy
- Quantity limits
- Deductibles
- Cost-sharing structure
That’s why looking only at a plan’s premium can be misleading.
“My copays are adding up.”
A $0-premium Medicare Advantage plan does not mean $0 healthcare.
Depending on the plan and services you use, you may have copays or coinsurance for specialists, outpatient procedures, diagnostic testing, hospital services and other care.
The important number isn’t simply:
“What’s my premium?”
It’s:
“What could this coverage realistically cost me based on the healthcare I use?”
What OEP Does NOT Let You Do
Understanding the restrictions is just as important.
OEP generally does not allow someone with Original Medicare to use this period simply to join a Medicare Advantage plan.
It also isn’t a general opportunity to jump between stand-alone Part D plans because you found another drug plan you like better.
And it isn’t three months of unlimited Medicare Advantage changes.
That’s why calling January 1 through March 31 simply “Medicare Open Enrollment” can create confusion.
The more accurate name is the:
Medicare Advantage Open Enrollment Period.
Those two words — Medicare Advantage — matter.
OEP and the General Enrollment Period Are NOT the Same Thing
Here’s another source of confusion.
The General Enrollment Period also runs from January 1 through March 31.
But it serves an entirely different purpose.
The General Enrollment Period primarily provides an opportunity for certain people who missed their opportunity to enroll in Medicare Part A and/or Part B to enroll.
The Medicare Advantage Open Enrollment Period deals with people already enrolled in Medicare Advantage who want to make an eligible change.
Same dates.
Very different rules.
Before Using OEP, Check These Five Things
If your Medicare Advantage plan isn’t working the way you expected, don’t switch based solely on frustration.
First, investigate exactly what isn’t working.
1. Your doctors
Verify your primary care physician and important specialists with the plan.
2. Your hospitals
For people here in Northwest Florida, hospital access can be particularly important.
Don’t assume your preferred hospital and affiliated physicians participate simply because the facility is nearby.
3. Your medications
Run your complete medication list against the alternative plan’s formulary and pharmacy network.
4. Your expected healthcare costs
Compare more than premiums.
Look at specialist copays, diagnostic services, outpatient procedures, hospital costs and the plan’s maximum out-of-pocket limit.
5. Your supplemental benefits
Dental, vision, hearing, over-the-counter allowances and other benefits can be useful.
But they shouldn’t distract you from the core medical coverage.
Your doctors, hospitals, prescriptions and medical costs come first.
The Best OEP Change May Be No Change at All
Here’s something you don’t hear very often in Medicare advertising:
Sometimes the correct answer is:
Stay exactly where you are.
Maybe a billing problem made it appear your plan wasn’t accepted.
Maybe your physician actually is in-network.
Maybe your prescription cost problem can be resolved by changing pharmacies.
Or perhaps after comparing the alternatives, your existing plan is still your best option.
A Medicare review doesn’t have to end with an enrollment.
Sometimes its greatest value is confirming that you already made a good decision.
A Second Chance — Not a Second AEP
That’s the simplest way to remember Medicare Advantage OEP.
January 1 through March 31 is not a repeat of Annual Enrollment.
It’s a limited second chance for people already enrolled in Medicare Advantage.
If your plan isn’t working as expected, you may have an opportunity to correct the situation.
But because you generally get only one OEP election, don’t make that change casually.
Check your doctors.
Check your hospitals.
Check your prescriptions.
Understand the costs.
And if you’re considering leaving Medicare Advantage for Original Medicare and a Medicare Supplement, investigate your Medigap eligibility before making the move.
How AJ Health & Wealth Can Help
Mark Garrett is a licensed independent Medicare broker serving Escambia and Santa Rosa counties, helping Medicare beneficiaries throughout Pace, Milton, Pensacola, Jay, and Gulf Breeze understand their Medicare options without all the jargon.
If January arrives and you’re thinking:
“I don’t think I chose the right Medicare Advantage plan,”
don’t panic — but don’t make a rushed change either.
Let’s review what isn’t working, compare the options available to you, and determine whether using your Medicare Advantage Open Enrollment opportunity actually makes sense.
There is no cost to you for our Medicare review services.
Not sure if the Medicare Advantage Open Enrollment Period applies to your situation?
AJ Health and Wealth helps Medicare beneficiaries throughout Pace, Milton, Pensacola, Jay, and Gulf Breeze review their coverage at no cost. Schedule a free consultation to talk it through.
Related Reading
- Most Pace and Milton Medicare Beneficiaries Throw This Letter Away — Here’s Why That’s a Mistake
- The Hidden Costs After a Hospital Stay: What Pace and Pensacola Seniors Should Know About Medicare
AJ Health and Wealth is not connected with the Federal Medicare program. By contacting this number, you will be connected with a licensed insurance agent. We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE or your local State Health Insurance Program to get information on all of your options.